
Are you properly insured in Switzerland? 6 situations that could cost you thousands of francs
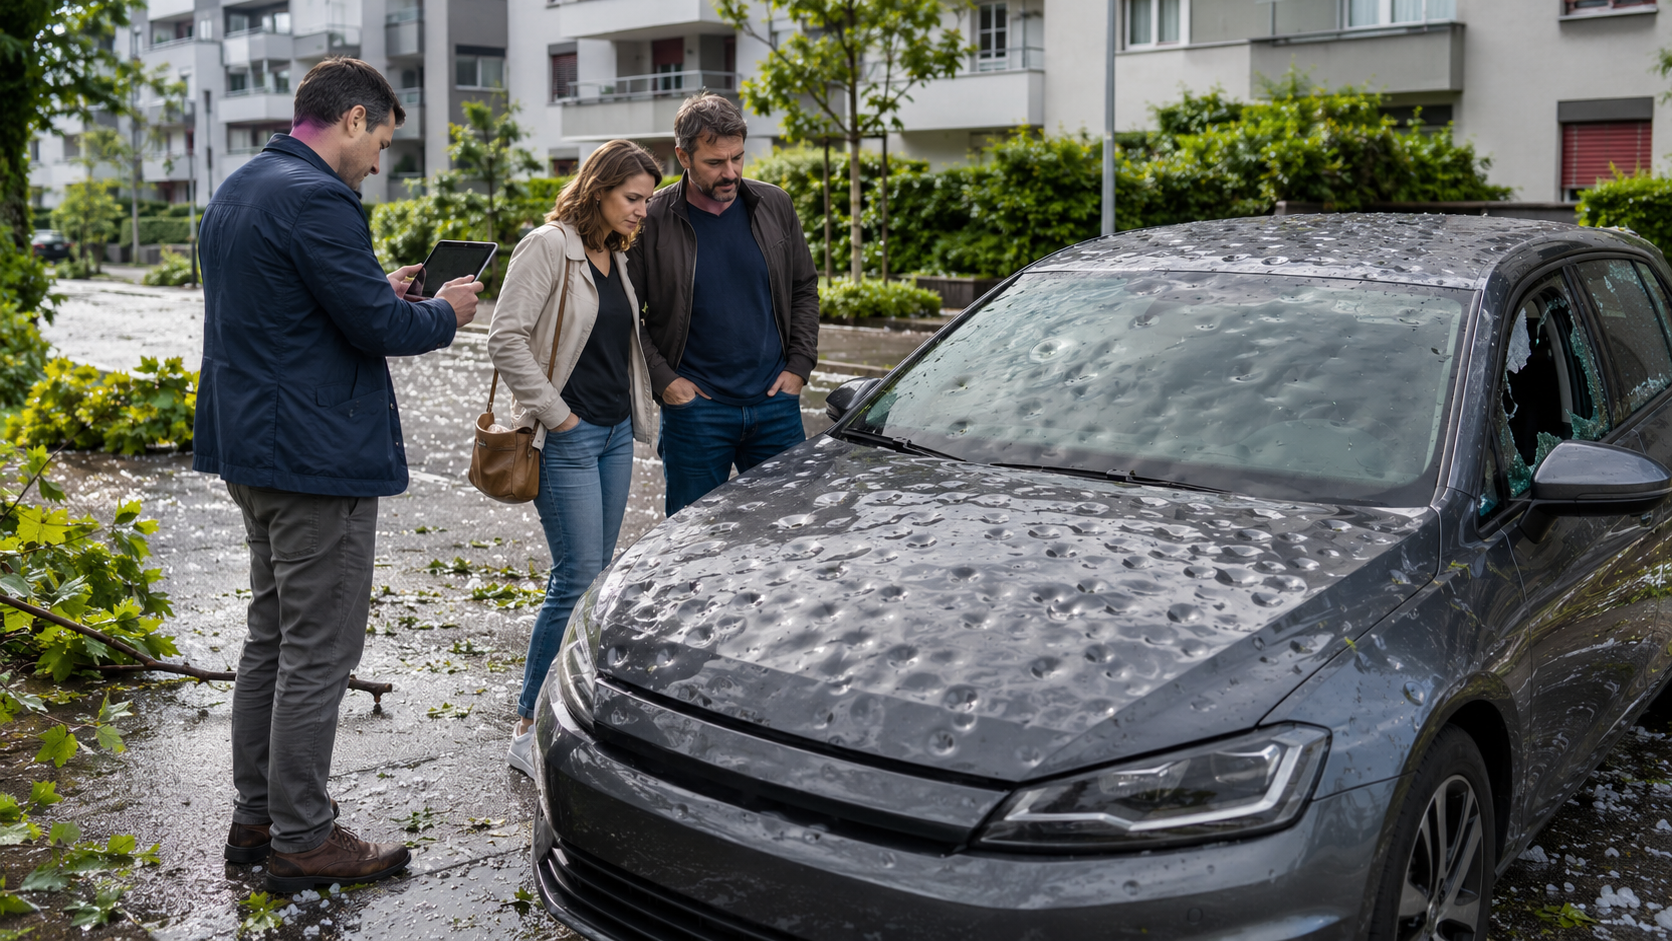
On Friday, 28 August, the weather changed within minutes in several parts of the canton of Zurich.
Large hailstones, strong winds, fallen trees, broken windows and extensive damage to vehicles and buildings.
According to SRF, by the following Monday, the Zurich Cantonal Building Insurance Institution (Gebäudeversicherung Kanton Zürich) had received approximately 11,600 claims and estimated the damage at around CHF 200 million.
The figures are striking. But behind every claim is a person, family or business dealing with the consequences.
And that raises a much more important question:
What would happen if it happened to you tomorrow?
What if…
Hail damaged your car?
A fire destroyed your personal belongings?
You accidentally caused CHF 20,000 worth of damage to another property?
You had a legal dispute with your employer or landlord?
You needed medical treatment that basic health insurance doesn't cover?
An online scam emptied part of your bank account?
We can't predict the next unexpected event.
But we can check today whether we're financially prepared for it.
Insurance doesn't prevent problems. It reduces their financial consequences.
An insurance policy can't stop a storm. It can't prevent an accident, a breakdown, a legal dispute or online fraud either.
Its purpose is different: to protect you financially when an insured event occurs and the policy conditions are met.
And there's one fundamental rule: most insurance coverage needs to be in place before the problem happens.
You can't take out car insurance retrospectively after hail has already damaged your vehicle.
Similarly, buying legal expenses insurance after a dispute has started doesn't mean that existing dispute will be covered.
That's why the best time to review your insurance is before you need it.
Free review · In English · No obligation
Having insurance doesn't necessarily mean you're properly protected
Many people know they have several insurance policies.
But they don't always know:
Which risks are covered.
The maximum insured amount.
What deductible they would have to pay.
Which family members are insured.
What exclusions apply.
Whether there are waiting periods.
Whether their coverage still matches their current circumstances.
Being properly insured doesn't mean buying every policy available. And it doesn't mean paying the highest premium.
It means having appropriate coverage, sufficient limits and no unnecessary overlaps.
Let's look at six examples.
1. Hail damage to your car: Having car insurance doesn't mean you're covered
In Switzerland, motor third-party liability insurance is mandatory to register a vehicle.
However, this insurance primarily covers your legal liability for damage caused to others.
It doesn't automatically cover hail damage to your own car.
Hail damage is generally associated with coverage such as:
Teilkasko: Partial comprehensive insurance.
Vollkasko: Fully comprehensive insurance, which generally includes partial comprehensive cover.
This means two people whose cars are parked next to each other during the same storm could face completely different financial consequences.
One might have the repair costs covered under their policy.
The other might discover that they only have third-party liability insurance.
What should you do if hail damages your car?
Prioritise your safety.
Take photographs and videos of the damage.
Record the location, date and time.
Report the claim to your insurer as soon as possible.
Avoid major repairs before receiving instructions from your insurer.
Take reasonable steps to prevent further damage, provided it's safe to do so.
2. A fire next door could destroy your belongings
A fire doesn't have to start in your own home to cause serious damage.
In one of the cases described here, a fire broke out in the apartment next to a client's home.
The client's apartment wasn't completely destroyed, but smoke, soot and fire seriously damaged clothing, textiles and other personal belongings.
The problem became clear afterwards: the client didn't have household contents insurance (Hausratversicherung).
Building insurance and household contents insurance are not the same thing.
Hausratversicherung can protect your personal belongings — such as furniture, clothing and electronic devices — against certain insured risks.
Without suitable coverage, replacing your belongings could become a significant financial burden.
3. A small accident could lead to a CHF 20,000 claim
A client went on holiday and left her cat at home.
While she was away, the animal managed to turn on a tap.
The resulting water leak flooded the apartment below.
The claim came close to CHF 20,000.
Because she didn't have private liability insurance, she had to face the financial consequences herself.
Private liability insurance (Privathaftpflichtversicherung) may cover your legal liability when you accidentally cause damage to someone else.
Depending on the policy, coverage may also extend to certain household members or damage caused by pets.
Examples include:
Damage to a rented apartment.
Accidents involving a bicycle.
An object falling from a balcony.
Damage accidentally caused by your children.
Everyday incidents that result in expensive claims.
A relatively affordable insurance premium could protect you against a much larger financial claim.
Of course, coverage always depends on the circumstances, legal liability and the terms of your policy.
4. Legal expenses insurance needs to be in place before a dispute
Legal problems can arise unexpectedly.
For example:
Unpaid wages or overtime.
Disputes about dismissal.
An incorrect employment reference (Arbeitszeugnis).
Problems with a landlord or property management company.
Defects in a rented property.
Contractual disputes.
Road traffic disputes.
Online shopping problems.
In another case described here, a client experienced a prolonged heating failure during winter.
Because the client already had legal expenses insurance, they were able to obtain advice, document the situation correctly and pursue a claim against the landlord.
The client eventually recovered approximately CHF 1,000 in rent.
The important point is that legal expenses insurance generally doesn't cover disputes that started before the policy became effective.
Waiting periods and other exclusions may also apply.
That's why legal protection is most useful when it's already in place before a conflict arises.
5. Supplementary health insurance: When you need it, it may be too late
Mandatory basic health insurance in Switzerland covers the benefits required by law.
Supplementary health insurance (Zusatzversicherung) may provide additional benefits, depending on the policy, such as:
Greater choice of hospital accommodation or providers.
Semi-private or private hospital stays.
Complementary and alternative medicine.
Preventive healthcare and fitness contributions.
Glasses and contact lenses.
Dental treatment.
Additional medical coverage abroad.
But there's a crucial difference between basic and supplementary insurance.
With supplementary insurance, insurers may ask questions about your medical history and are generally not required to accept every applicant.
This means that waiting until a diagnosis or specific medical need arises could make it difficult or impossible to obtain certain benefits.
If you're considering switching supplementary insurers, don't cancel your existing policy until you've received written confirmation that the new insurer has accepted your application.
You should also check that the new coverage is suitable and that you can meet your existing policy's cancellation deadline.
6. A fake link could cost you thousands of francs
Risks aren't only physical anymore.
They're digital too.
In another case described in this article, a client advertised an item for sale on Ricardo.
Shortly afterwards, the client received a message containing what appeared to be a legitimate payment link.
The website looked convincing.
After entering their details, unauthorised charges or transfers of around CHF 250 began appearing.
The total loss eventually approached CHF 5,000.
Certain CyberRisk insurance policies may offer assistance and financial protection for specific types of online fraud.
However, you should never assume this coverage is automatically included.
It's important to check:
Which cyber risks are insured.
Maximum compensation limits.
Deductibles.
Exclusions.
Security and due-care obligations.
What should you do if you're a victim of online fraud?
Contact your bank or card issuer immediately.
Block affected cards, accounts and access credentials.
Change compromised passwords.
Save messages, links, screenshots and transaction details.
Report the incident to the police.
Notify your insurer if you have relevant CyberRisk coverage.
Are you self-employed or running a business?
Business risks deserve a separate insurance review.
Personal insurance policies don't automatically cover losses arising from your professional or business activities.
Depending on your business, you may need to consider:
Business liability insurance.
Professional indemnity insurance.
Business legal expenses insurance.
CyberRisk coverage.
Business equipment and inventory insurance.
Business interruption insurance.
Daily sickness allowance insurance (Krankentaggeld).
Mandatory employee insurance.
A hair salon, cleaning company, transport business and independent consultant don't face the same risks.
That's why insurance protection should reflect what your business actually does.
You don't need more insurance. You need the right insurance.
My goal isn't to encourage you to take out another policy just because a storm has recently caused major damage.
The storm is simply a reminder of something important:
Once something happens, you can't retrospectively change the insurance protection you had at the time.
A proper insurance review should consider:
✓ Your personal, family or business circumstances.
✓ Your existing insurance policies.
✓ What is actually covered.
✓ Insured amounts and deductibles.
✓ Important exclusions.
✓ Waiting periods.
✓ Potential overlaps between policies.
✓ Significant risks that may not be covered.
✓ Renewal and cancellation deadlines.
A good review should also tell you when your current insurance is already suitable and there's no reason to change anything.
Do you know what would happen if you had to make an insurance claim tomorrow?
If you're unsure, we can review your situation together.
You can send me your existing policies, and we'll look at:
Car insurance.
Household contents and private liability insurance.
Legal expenses insurance.
Basic and supplementary health insurance.
CyberRisk coverage.
Insurance for self-employed professionals and businesses.
I'll explain clearly:
What you're currently covered for.
Where there may be gaps.
Whether you're potentially paying more than necessary.
Which benefits or policies may no longer be relevant.
Review my insurance policy
Free initial review · In English · No obligation
About me
I'm Jesús Gómez, a FINMA-registered insurance advisor in Switzerland (registration number F01575262). I help people living or working in Switzerland understand their insurance options and choose coverage that suits their circumstances.
My main services include: