
Personal liability insurance in Switzerland
One careless moment can cost far more than you think. Personal liability insurance isn’t compulsory in Switzerland, but it’s one of the most important policies you can have. It covers damage you accidentally cause to other people or their property — at home, out and about, playing sport or travelling.
Request a free consultation → Free initial consultation · Independent advice · No obligation
What does personal liability insurance cover?
Accidents happen. A fall that injures someone, something you break at a friend’s place, damage you cause by accident while playing sport. In Switzerland, if you cause damage to a third party, you are personally liable — and compensation claims can be very high.
Personal liability insurance covers those costs. Without it, you pay them yourself.
If you break or damage something that belongs to someone else, the insurance covers the cost of repair or replacement.
If someone is hurt in an accident you cause, the insurance covers medical costs, loss of earnings and other compensation.
If someone claims compensation you don’t owe, the insurance also covers your legal defence.
Damage you cause to the flat you rent — even accidentally — is also usually covered, depending on the policy.
Many Swiss personal liability policies provide worldwide cover, subject to the policy’s terms and exclusions — so damage caused on holiday can be covered too.
Optional cover and additional protection
Basic cover protects you in most everyday situations. But depending on what you do, it can make sense to add specific cover.
If you fly drones or remote-controlled aircraft, you can add cover for damage caused while using them.
Cover for damage caused by pets varies between insurers. I’ll help you check whether your policy includes the animals you own.
If you sometimes drive a car that isn’t yours, you may be covered for damage you cause in those situations.
Both homeowners and tenants have specific situations covered. Minor building work and damage to a rented property are usually included.
With this extra cover, the insurer generally waives its right to reduce payouts for gross negligence — within the limits and exclusions of your policy.
If you hunt, ride horses or do sports with a higher risk of accidents, there are specific extensions available.
Everyday situations where liability insurance can help
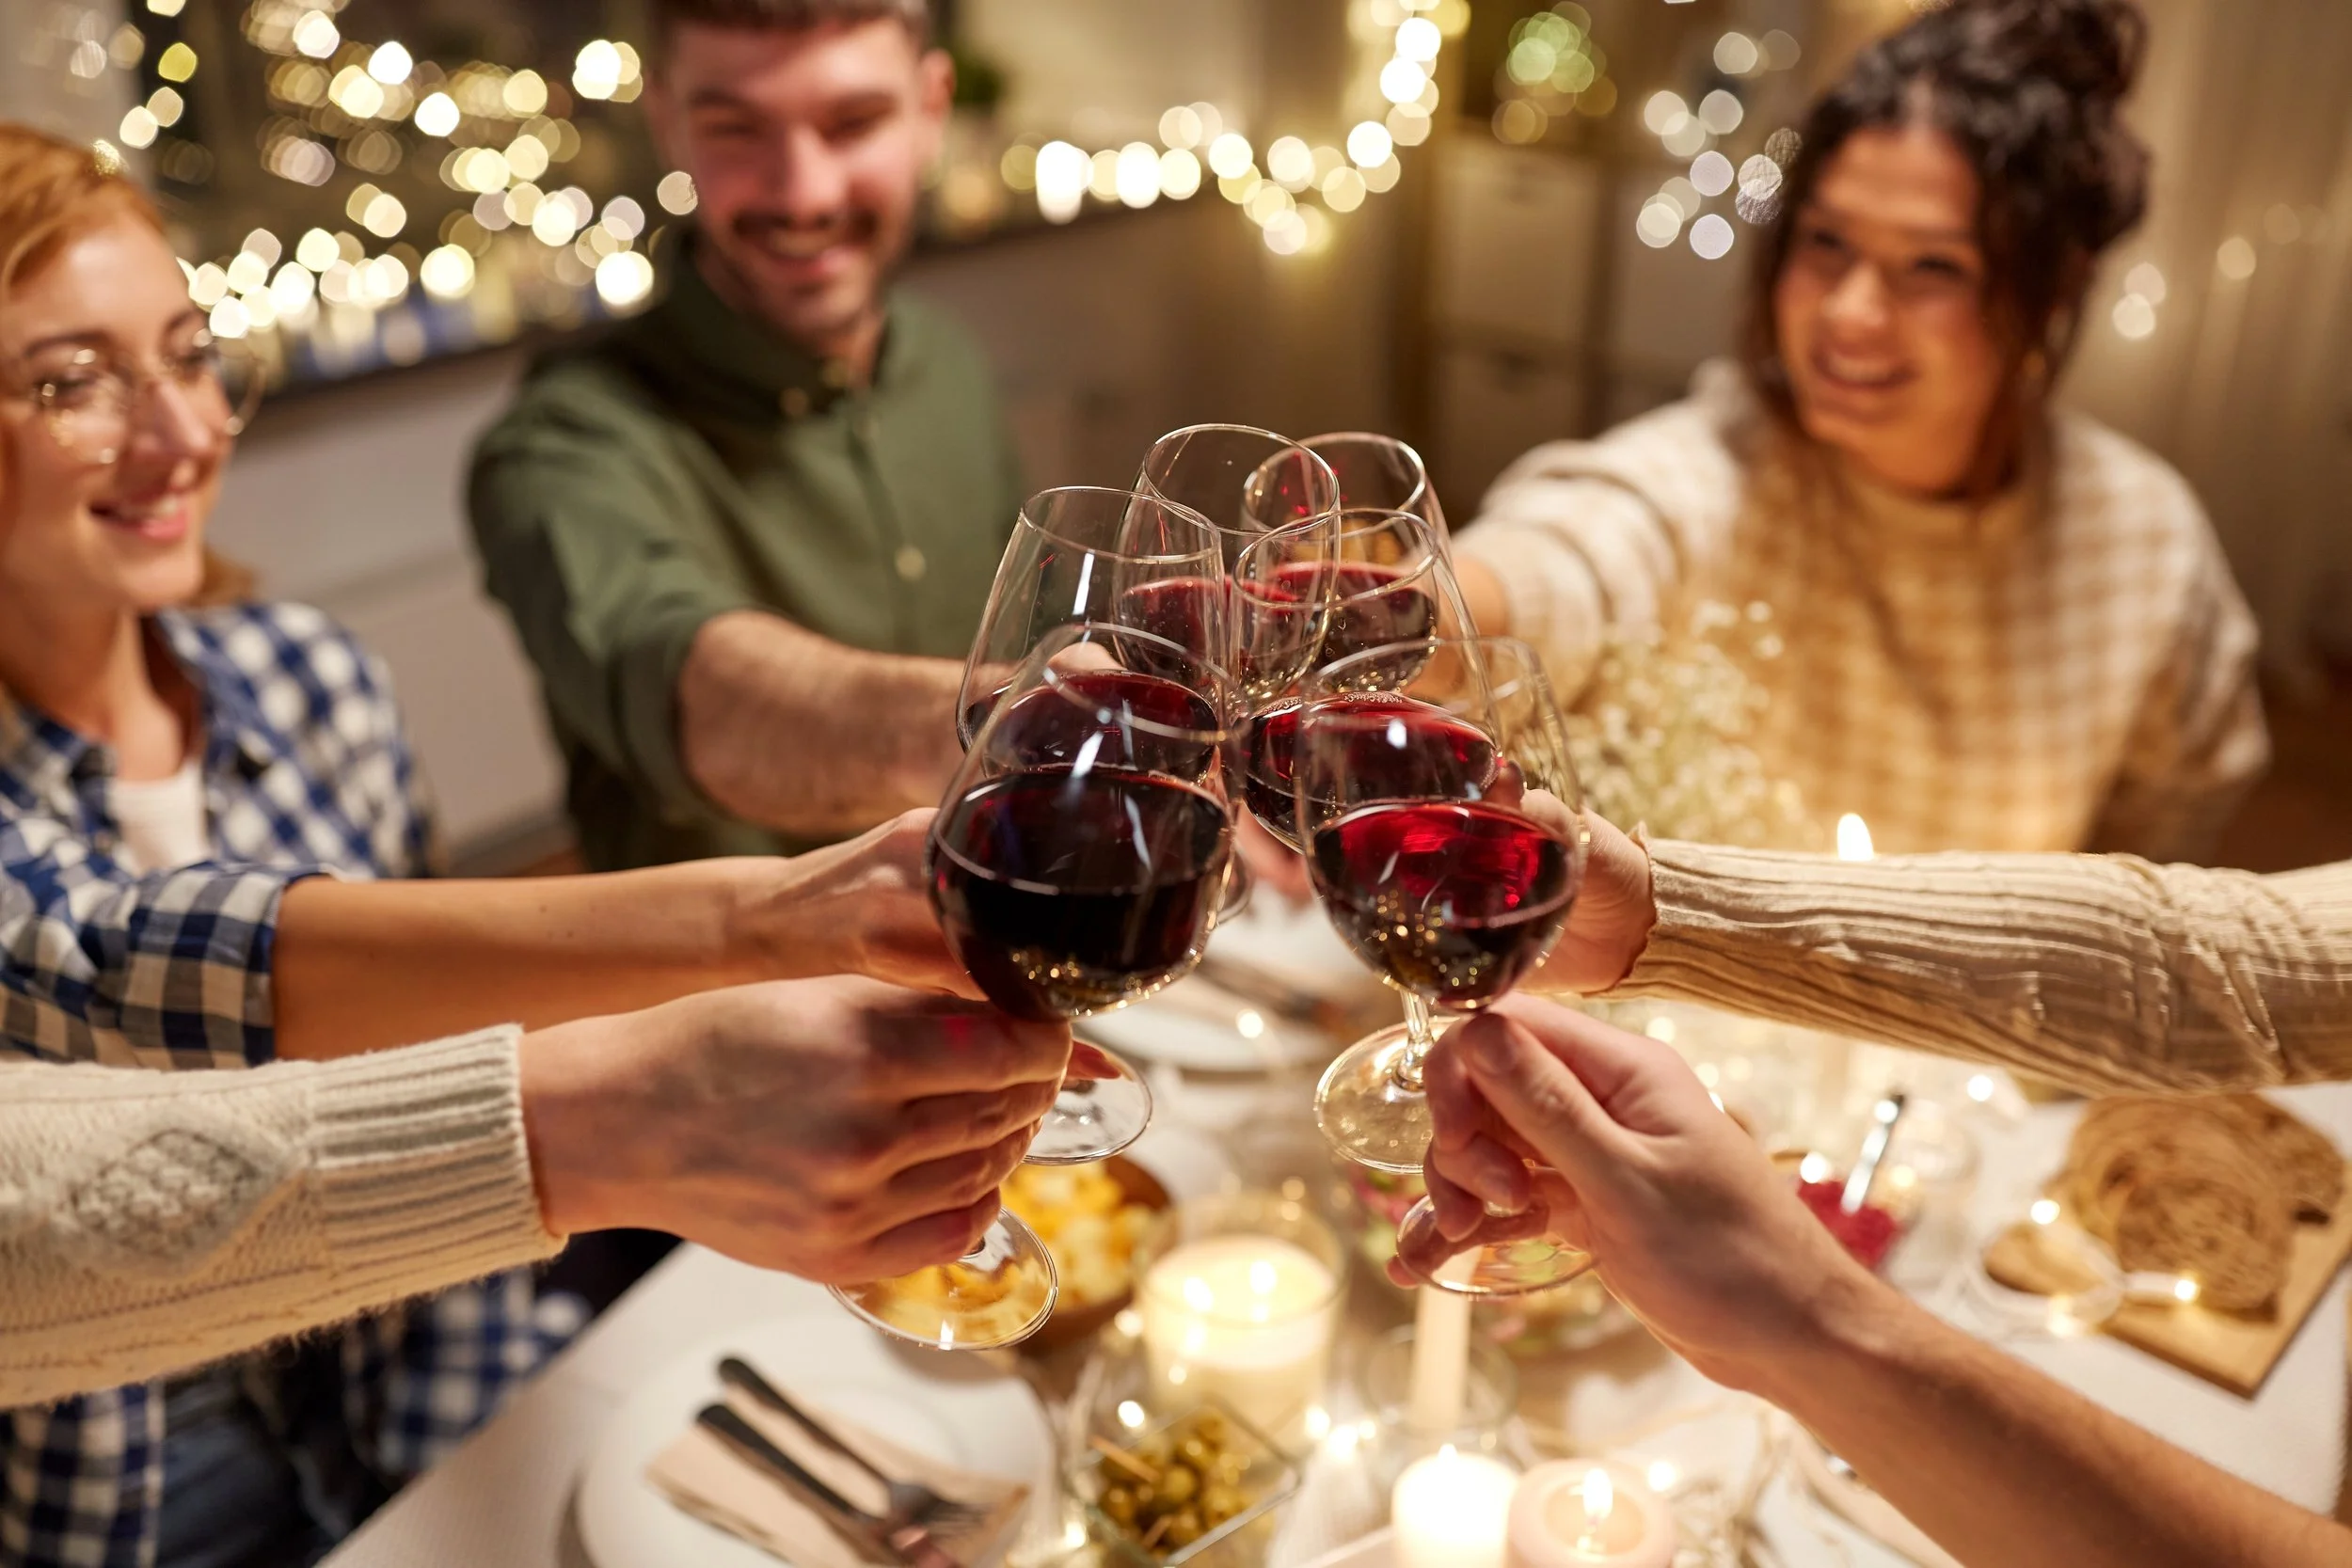
At a dinner with friends, she picks up a bottle of wine and it slips out of her hands. The glass table breaks and the wine stains an expensive rug. The damage comes to more than CHF 900.
Personal liability insurance covers damage to other people’s property. Without it, Elena pays for the table and the rug cleaning out of her own pocket.
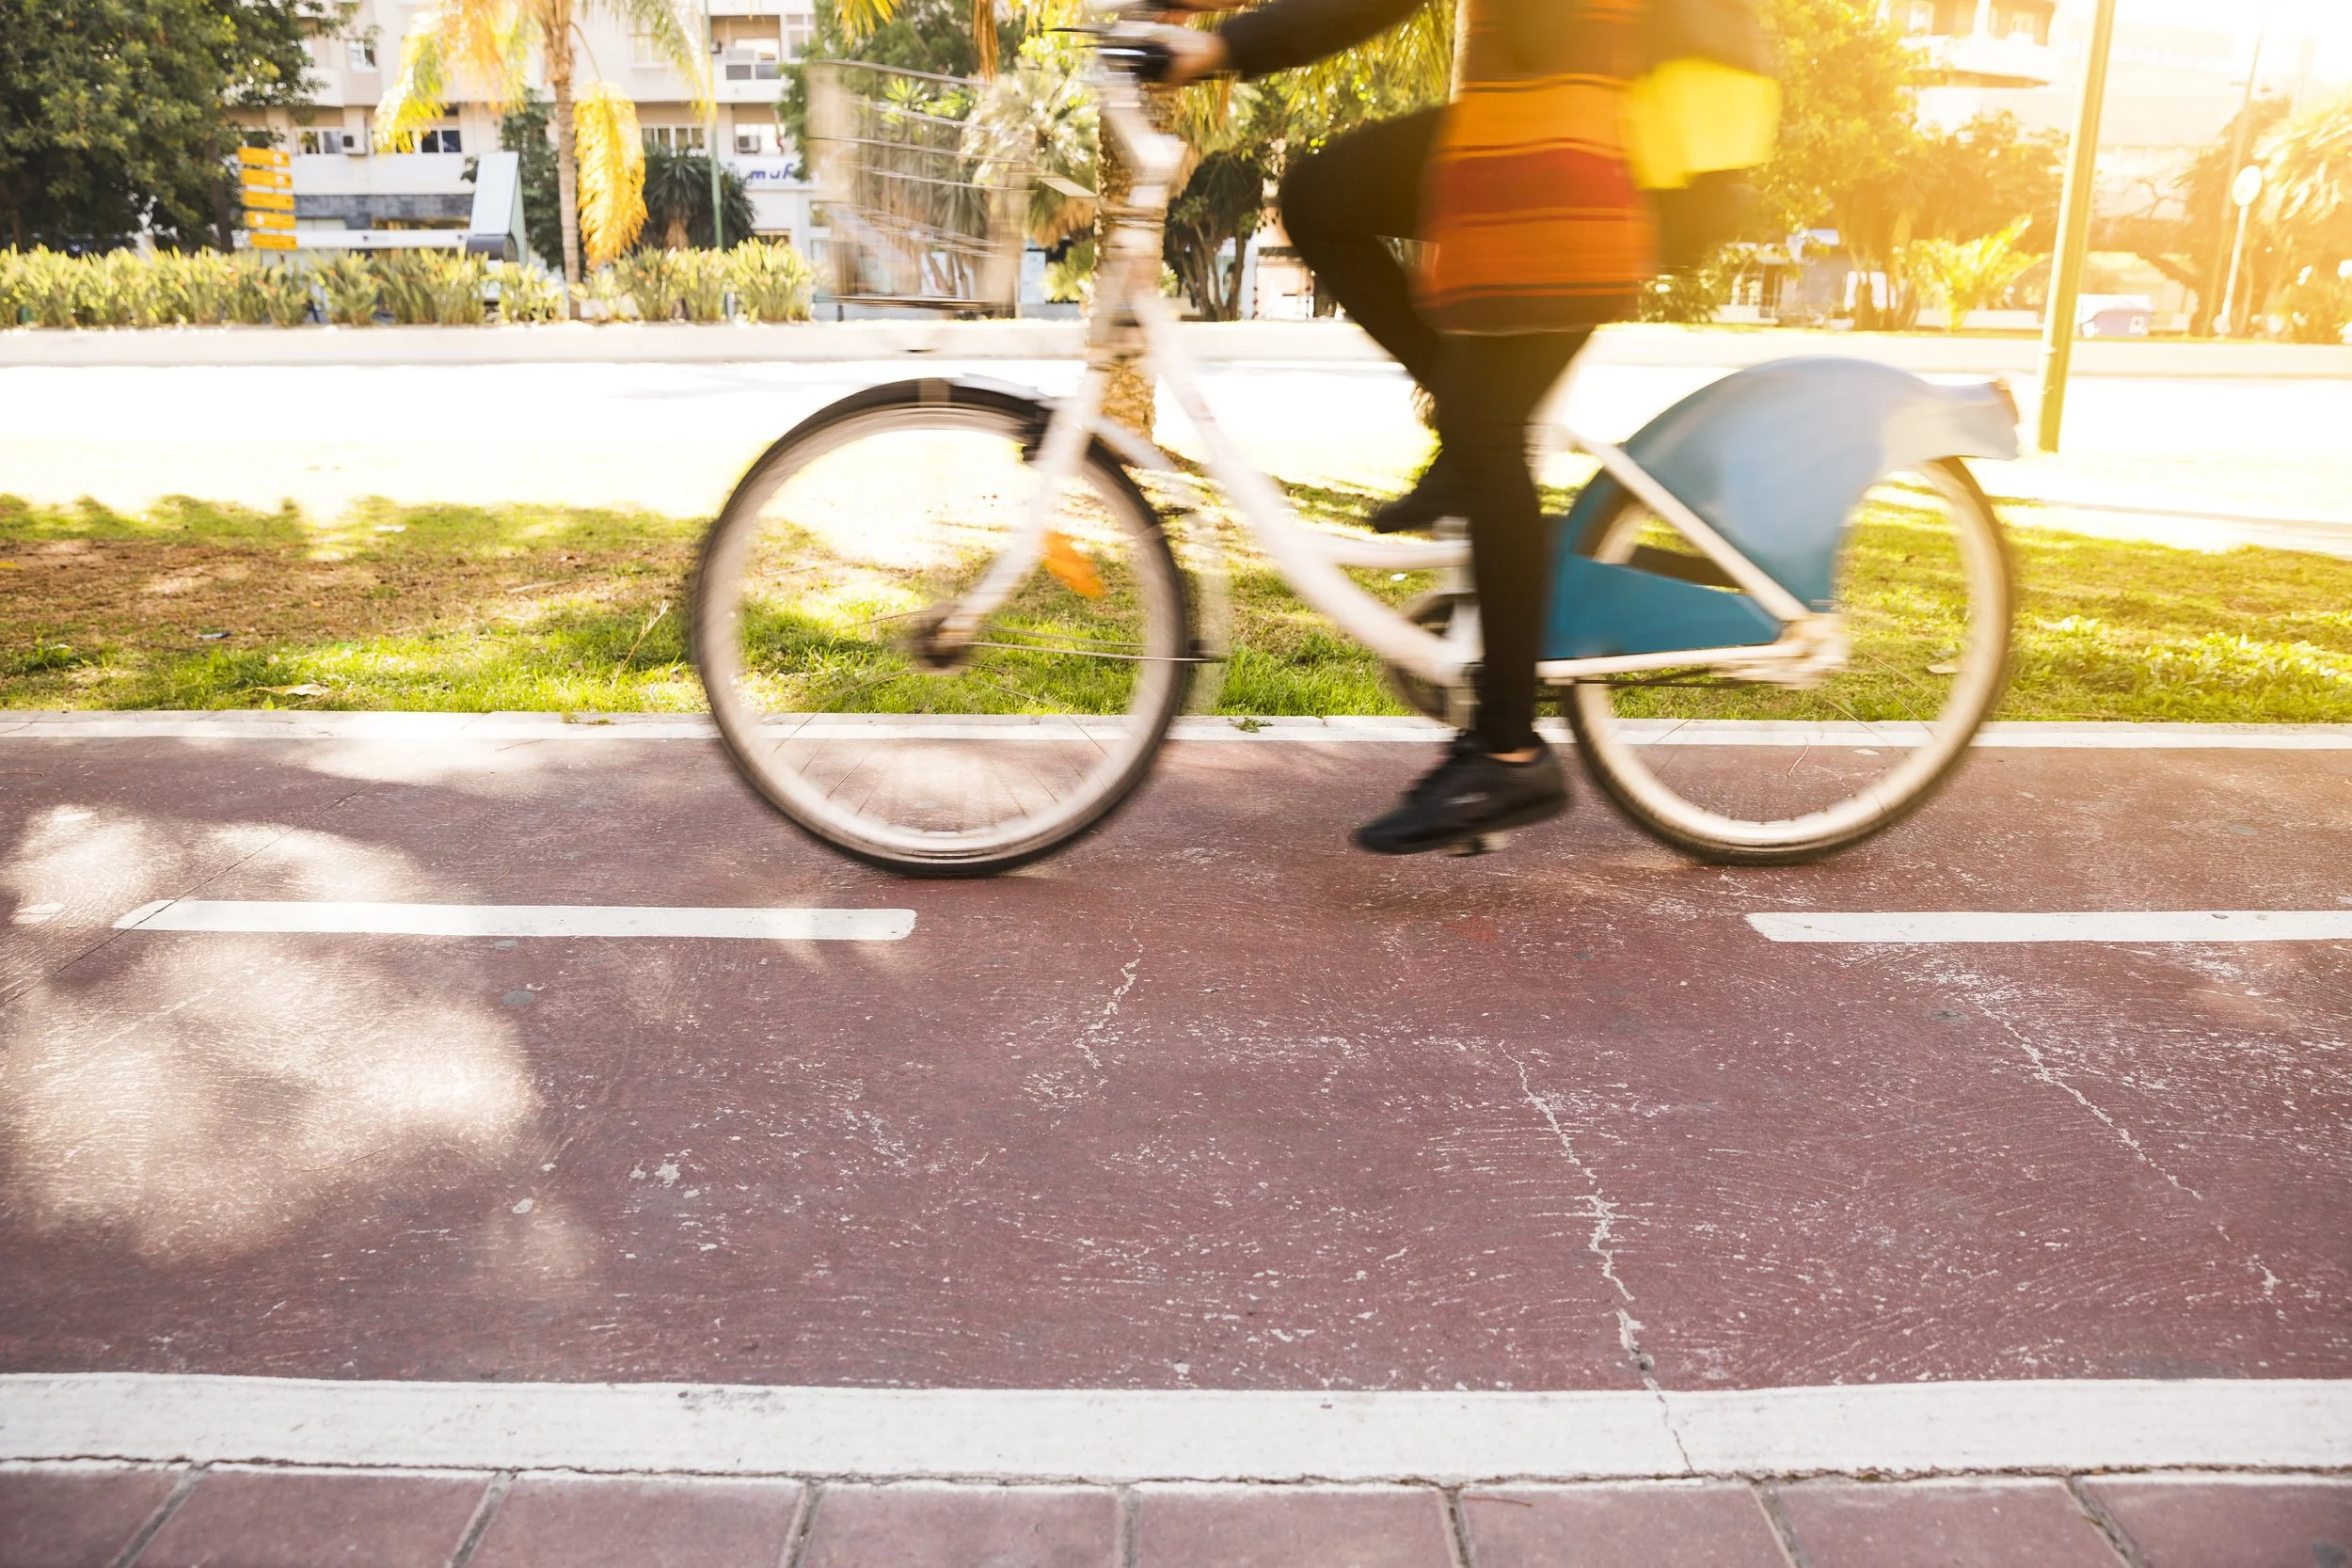
While cycling, he hits a pedestrian he didn’t see on a bend. The pedestrian falls, breaks a wrist and needs physiotherapy. Medical costs and temporary loss of earnings come to more than CHF 8,000.
Personal liability insurance covers injury to third parties, including medical costs and compensation for loss of earnings. Without it, Marcos pays the full amount.
She forgets to turn off the bath tap. The water overflows and damages the ceiling of the flat below. The building owner claims CHF 4,500 for the damage.
Damage caused as a tenant is covered by personal liability insurance. Without it, Carla would pay for the full repair of her neighbour’s ceiling.
These cases are hypothetical examples for illustration only. Actual cover depends on each policy and insurer.
It isn’t compulsory. But if you cause a serious accident, not having it can be very expensive
In Switzerland, your personal liability for damage to others has no upper limit. Your insurance does — and it covers you up to that amount.
How I help you choose the right cover
It’s a simple policy, but there are details worth checking: the sum insured, the deductible, optional extras, and whether to choose individual or family cover. I usually recommend it without a deductible, but I’ll explain why in each case. One conversation is enough to make everything clear.
Is personal liability insurance compulsory in Switzerland?
It isn’t required by law, but it’s one of the most advisable policies to have. In Switzerland, if you cause damage to a third party, you are personally liable with no legal upper limit. A serious injury can lead to a claim of hundreds of thousands of francs. Many landlords also require it before signing a rental contract. Your insurance sets that limit for you.
What’s the difference between individual and family cover?
Individual cover only protects the policyholder. Family cover protects everyone living in the same household: partner, children and other family members. Family policies may also cover children who live away from home, depending on their age, circumstances and the insurer’s terms. The difference in premium is usually small, and the extra cover is very worthwhile if you have a family.
Does it cover damage caused by children or pets?
It depends on the policy. With family cover, damage caused by children living in the household is usually covered. Cover for dogs and other animals varies between insurers — some include it, others require additional cover. It’s one of the points worth checking before you sign.
How much does personal liability insurance cost in Switzerland?
As a general indication, the annual premium is usually between CHF 150 and CHF 250, depending on cover and insurer. It’s one of the best-value policies on the Swiss market. Choosing the highest sum insured (CHF 10 million rather than CHF 3 million) usually makes only a minimal difference to the premium.
Already have personal liability insurance, or taking it out for the first time?
In one conversation, I’ll tell you which cover really makes sense for your situation. No jargon, no unnecessary small print.