
Home insurance in Switzerland
I help you understand what home insurance in Switzerland really covers, which extras may make sense for you and how to choose a clear policy that protects your home, your belongings and your peace of mind.
Review my home insurance → Free initial consultation · Independent advice · No obligation
What home insurance in Switzerland can cover
Not every policy covers exactly the same things, and not everyone needs the same add-ons. What matters is understanding what the basic cover includes and which optional extras make sense for the way you live.
Protection against the most common types of damage: fire, smoke, flooding, storms, hail and other natural hazards, depending on your policy.
✓ Basic coverCover for burglary and theft at home, helping you replace stolen items under the terms of your policy.
✓ Basic coverMany policies include, or let you add, cover for broken glass in furniture and fittings: ceramic hobs, washbasins, bathtubs or mirrors, depending on the insurer.
✓ Depends on the policyTheft away from home, luggage, valuables, accidental damage to your phone or laptop, earthquakes, or fraudulent use of cards and phones.
○ Optional coverWhat changes when you have the right cover
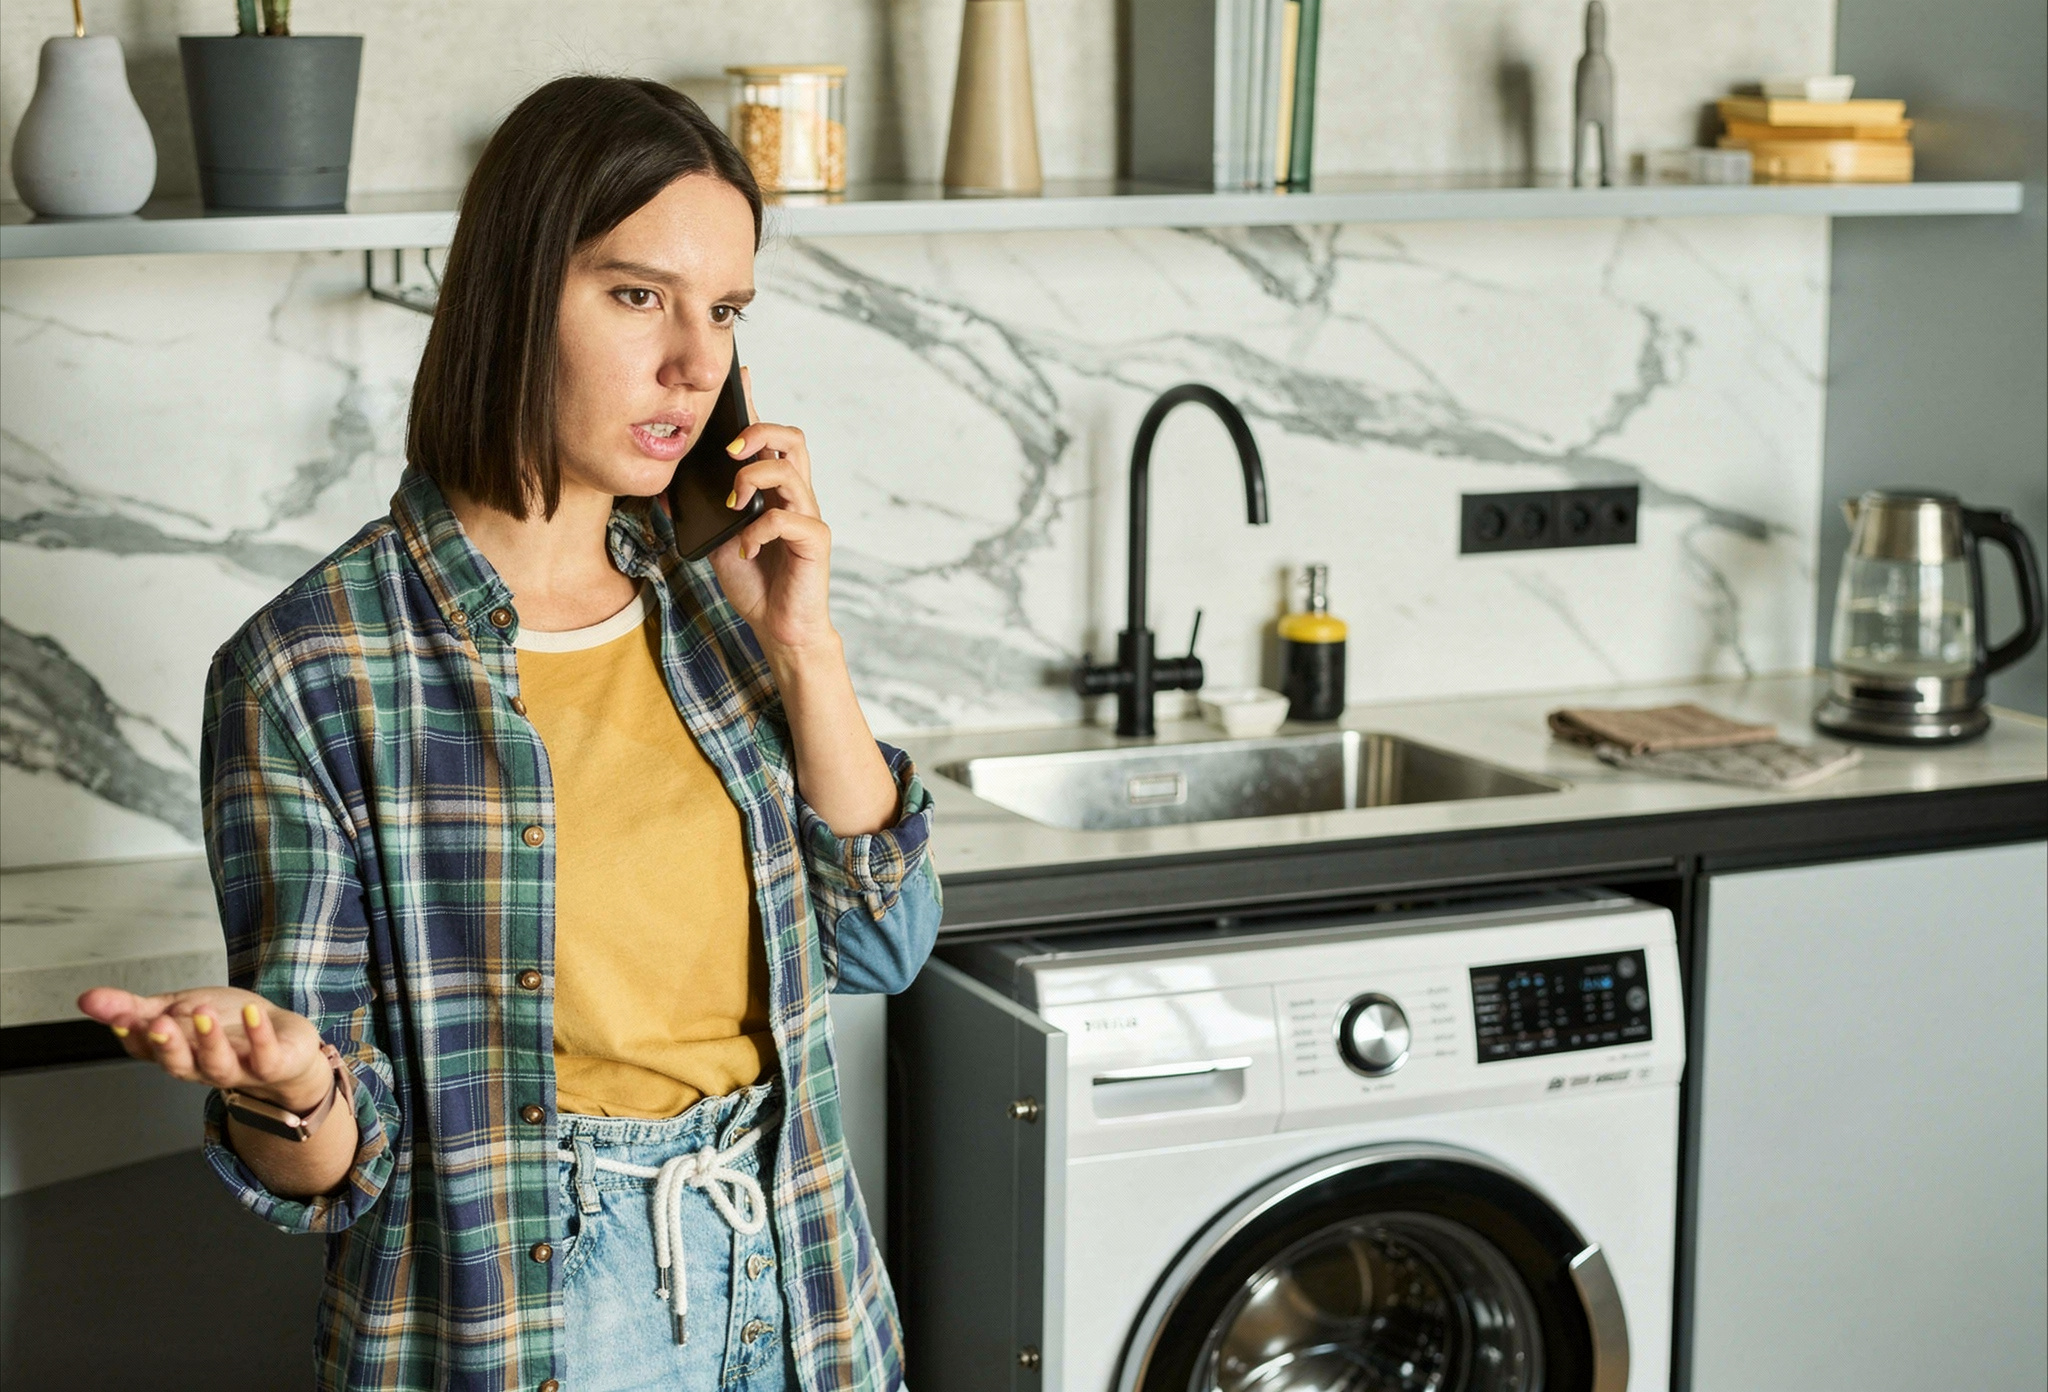
They come back from a weekend away to find their flat flooded by a faulty washing machine in the flat upstairs. Several pieces of furniture are damaged.
With home insurance that includes water damage, their damaged belongings would be covered. Without it, they would have paid the cost themselves while liability with the neighbour was sorted out.
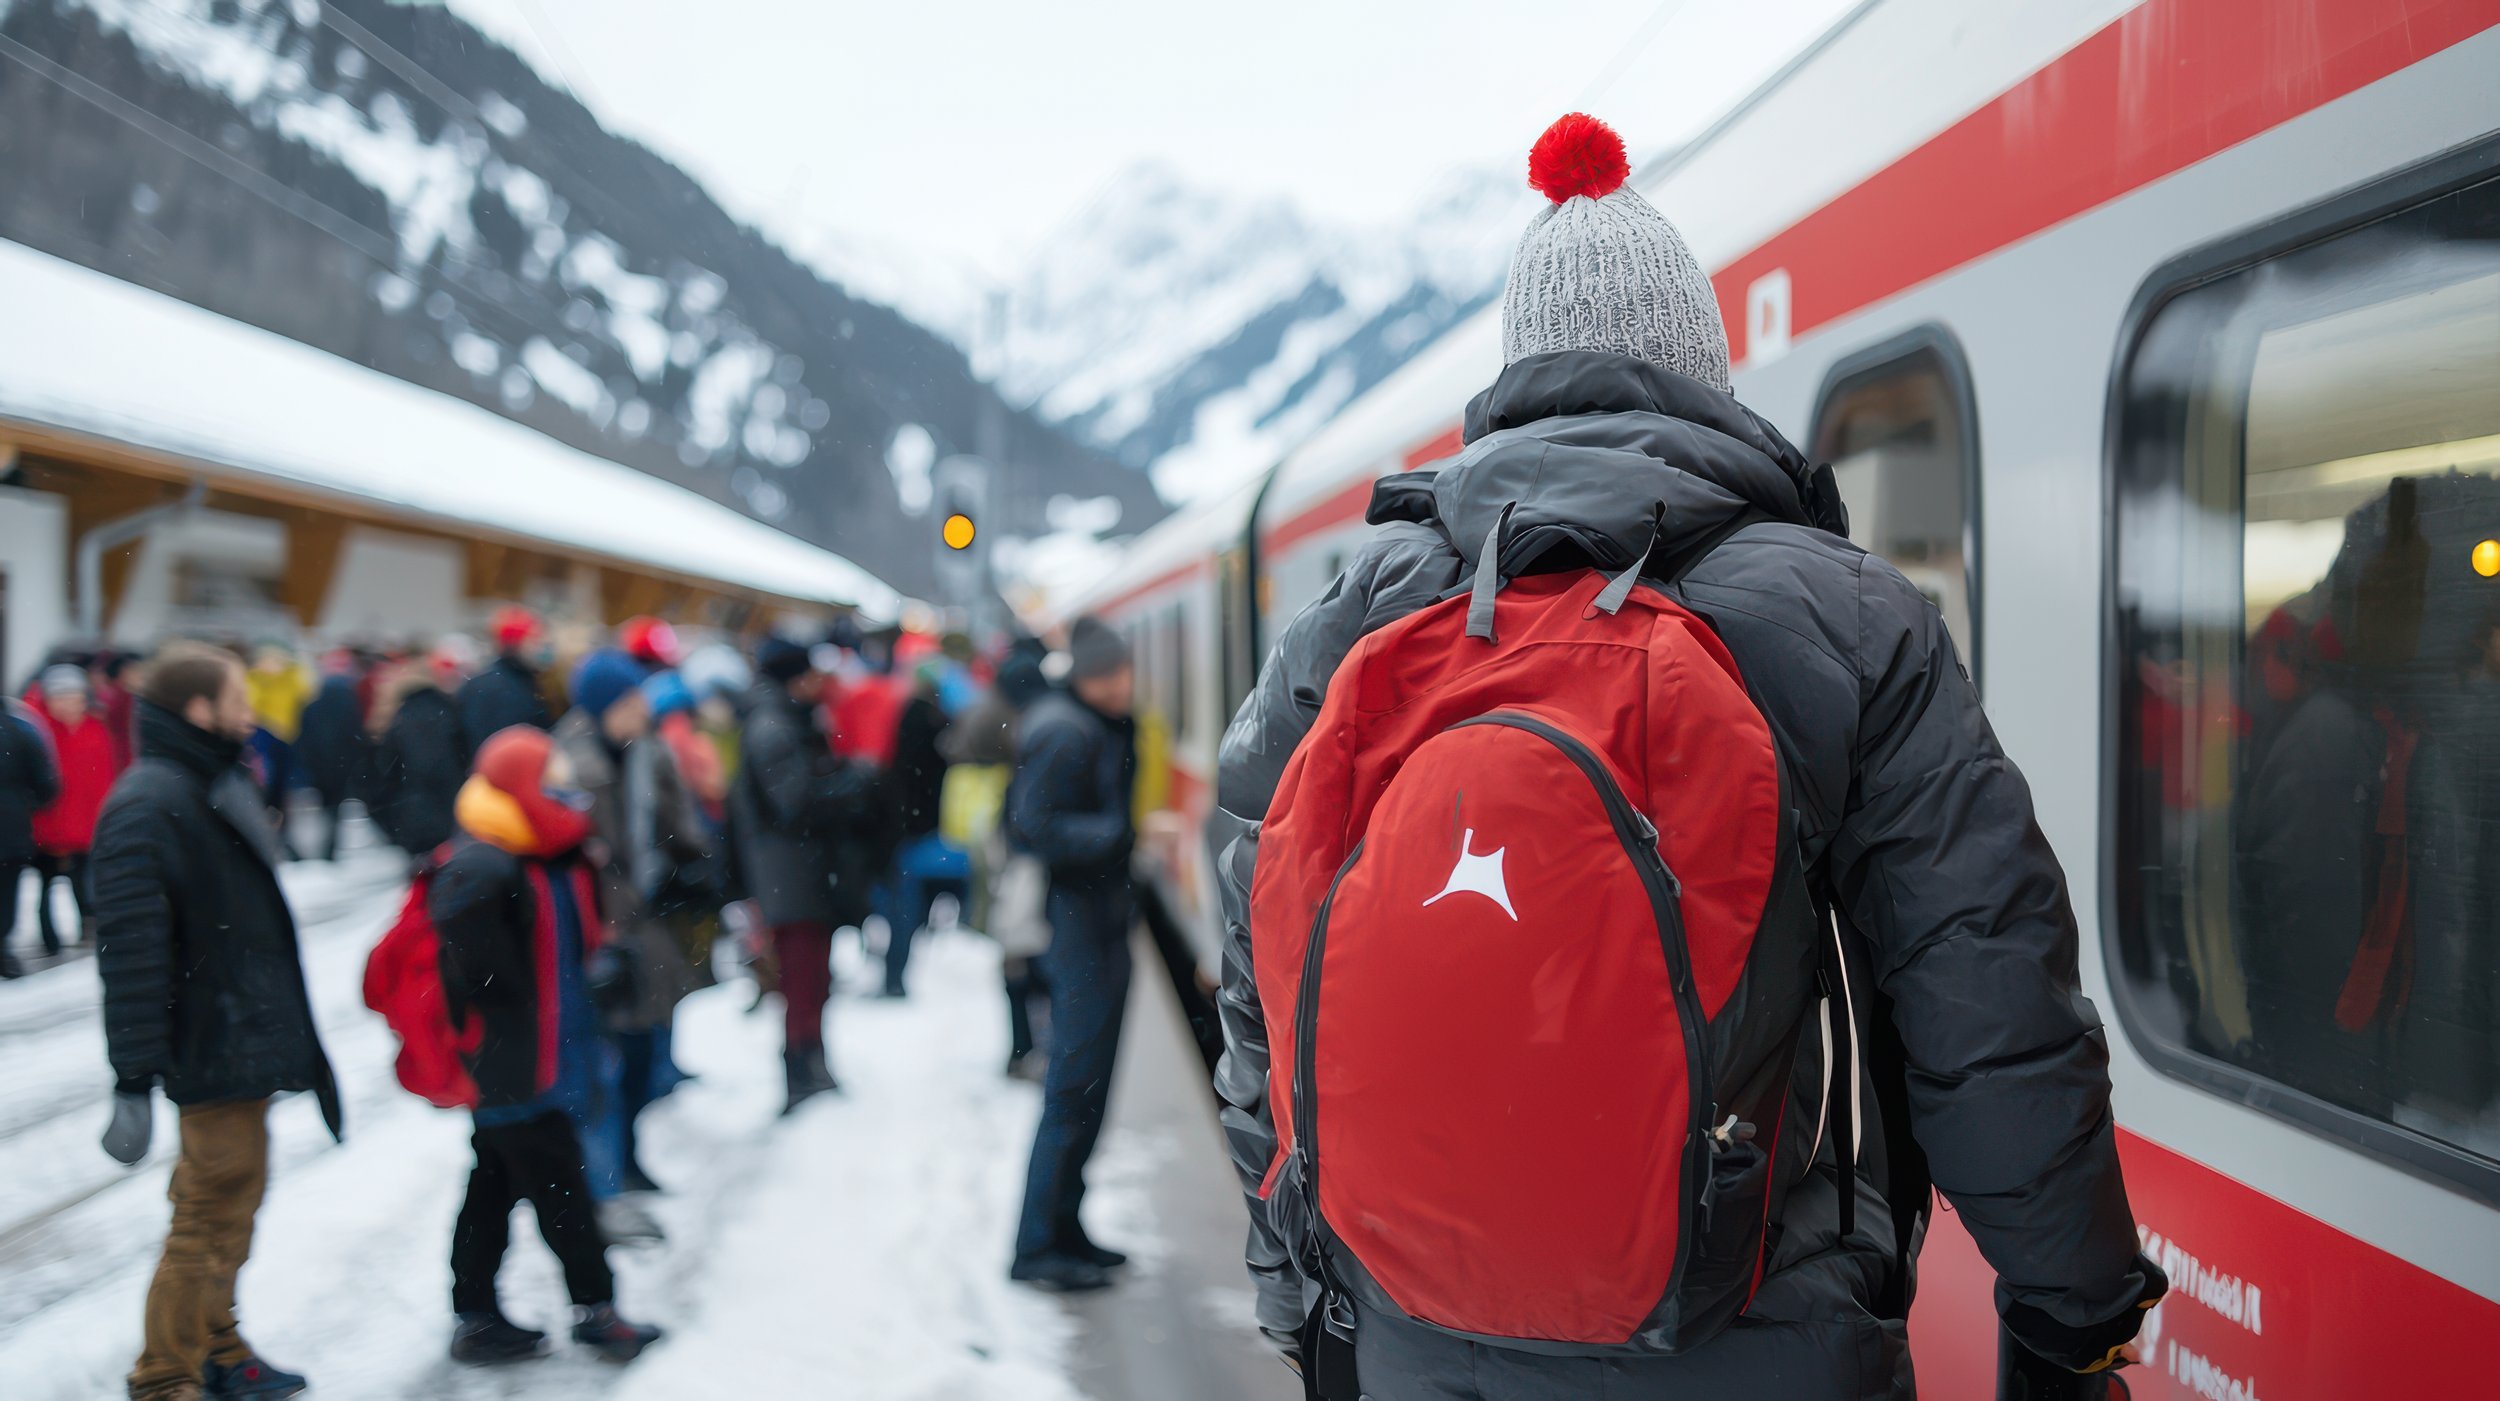
His rucksack is stolen on the train home from work. Inside are his laptop, headphones and wallet. The theft happens away from home.
With cover for theft away from home, the insurer would replace the laptop and other items. Without that add-on, the basic cover wouldn't pay out, because it happened outside the home.
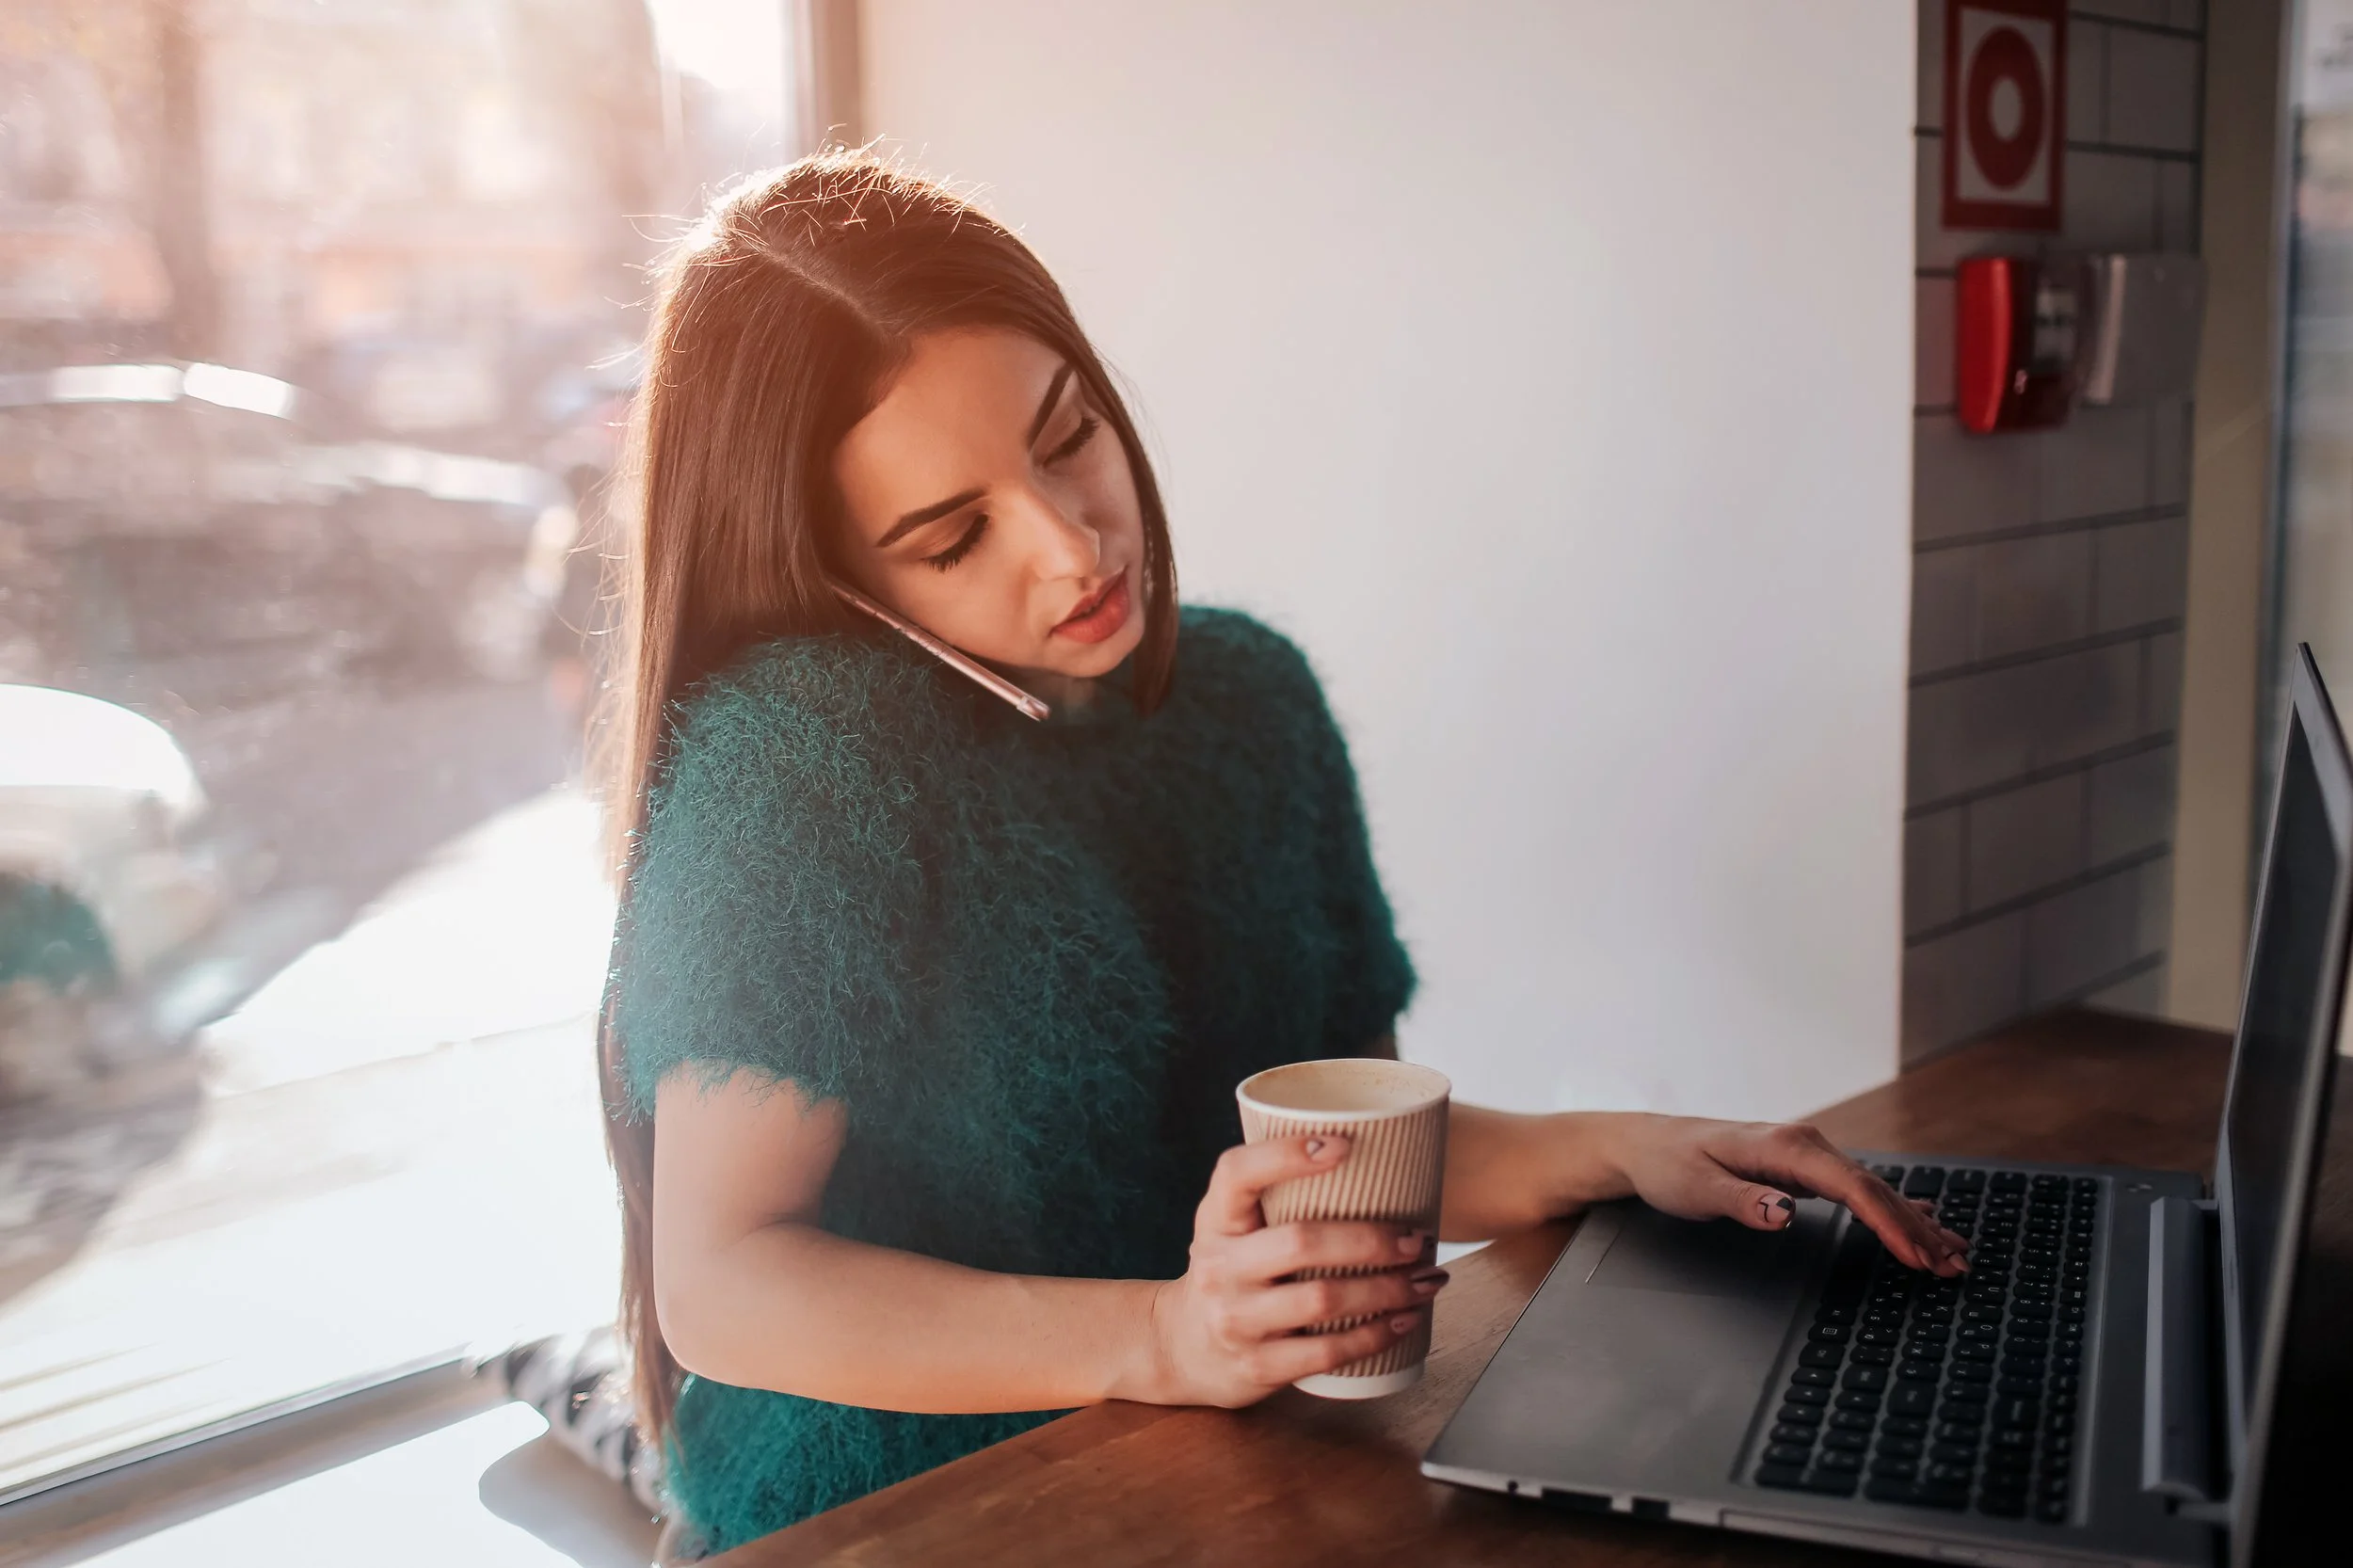
While working from home, she spills coffee on her laptop. Black screen, files out of reach, work at a standstill.
With accidental damage cover, the insurer would replace the laptop. Without it, an accident like this at home wouldn't be covered by the basic policy.
These cases are hypothetical and for illustration only. Actual cover depends on each policy and insurer.
What to check before you sign
Furniture, clothes, laptop, phone, bike, jewellery… it all adds up. If you're underinsured, your payout can be reduced even when the cover exists.
If you travel, have a laptop or an e-bike, or want cover for theft away from home, basic cover may not be enough.
This is what you pay yourself when you make a claim. The higher the deductible, the lower the premium. You can often choose between CHF 200, 300 or 500.
Homeowners may need extra cover for building glass, the garden or plants, which usually calls for advice.
The problem isn't having no insurance. It's not knowing what it covers
Many people only discover the gaps in their policy after something has gone wrong. Checking beforehand takes very little.
How I help you choose the right home insurance
It's not about buying more cover, it's about buying the right cover. We look at your actual situation and find the policy that fits.
What does home insurance cover in Switzerland?
It usually covers major risks such as fire, water, natural hazards and burglary. Many policies also include broken glass in furniture and fittings, such as ceramic hobs, washbasins or bathtubs. What varies from one policy to another are the optional extras and the limits on each type of cover.
Does it cover theft away from home?
Not always as part of the basic cover. Theft away from home is often an add-on you have to choose specifically. If you travel a lot or carry valuables with you, it's worth checking before you sign.
Can I insure my phone, laptop or jewellery?
Yes. Depending on the insurer, there may be add-ons for accidental damage, valuables, luggage or theft away from home. Your phone or laptop, for example, usually needs specific accidental damage cover to be protected against breakages and everyday accidents.
Which deductible should I choose?
It depends on your situation and how much risk you're comfortable with. Many Swiss insurers let you choose between CHF 200, CHF 300 or CHF 500. The higher the deductible, the lower the premium usually is. In the consultation we work out which level suits you best.
Is it the same for tenants and homeowners?
No. If you own your home, you may need extra cover for building glass, windows, balcony doors, the garden or plants. These add-ons usually need to be arranged through an advisor and aren't always available online.
Is home insurance compulsory in Switzerland?
There's no federal requirement, but it depends on the canton. For homeowners, buildings insurance is compulsory in most cantons. Contents insurance is usually optional, although some cantons, such as Vaud, require at least cover against fire and natural hazards. Either way, it's one of the most worthwhile policies for anyone who wants to protect their belongings against damage or theft.
What happens if I'm underinsured?
If the sum insured is lower than the real value of your belongings, your payout can be reduced in the same proportion. That's why it's worth reviewing the sum insured regularly, especially when you move or buy valuable items.
Already have home insurance, or thinking of taking some out?
I'll review your current cover or help you find the option that best fits your situation in Switzerland. Clear advice, no obligation.